Learn how we are working to transform how we use and produce energy.
How Better Policy Can Support Japan’s Green Steel Opportunity
An analysis of policy impacts on low-emissions steelmaking in Japan
Why we share this work for free
RMI is an independent nonprofit working to accelerate the clean energy transition. We publish research like this to inform decision-makers and drive real-world impact.
Our work is supported by philanthropy as well as partnerships, including fee-for-service engagements. This support makes it possible for us to share our independent insights for free.
If you find this work valuable, you can support it anytime.
Get more insights like this
Stay up to date with the latest research, analysis, and tools from RMI by opting in to receive occasional emails below. You’ll get new reports, event invitations, and practical insights to help us all accelerate the clean energy transition.
Loading form...
Your download should start automatically. If it doesn’t, click the download button below.
This work is made possible by philanthropy
RMI is a nonprofit supported by donors and partners. Philanthropy enables us to produce independent research and make resources like this freely available.
If you find this report valuable, please consider supporting our work. You can also explore how we partner with organizations to drive impact.
Jump to Section
Key Takeaways
A Transition to Cleaner Steelmaking Can Build Resilience and Competitiveness
Japan is the third largest steelmaker in the world, producing 84 million tons (Mt) of crude steel in 2024.1 The steel sector currently accounts for 14% of Japan’s total emissions, with coal-based blast furnace-basic oxygen furnace (BF-BOF) constituting 74% of production.2 Emission-intensive steelmaking will face rising costs, as policies such as the European Union’s Carbon Border Adjustment Mechanism (EU CBAM) will put an estimated US$14 billion to $28 billion of Japan’s economic value at risk from 2026 to 2050.3
Other importers of Japanese steel, such as Australia, Canada, and the United Kingdom, are considering or actively implementing CBAMs, which would put nearly 1 million additional tons of exports per year at risk.4 This exposure may increase as the EU is considering extending CBAM to steel embedded in some manufactured goods. Japan’s recently enacted emissions trading system (GX-ETS) is also expected to impose additional costs in the coming years.
At the same time, demand for low-emission steel is growing globally. Estimated voluntary near-zero demand in Asia Pacific (not including China and India), Europe, and North America is about 20 Mt in 2030. Around 80% of this estimated demand will be for ore-based products, underscoring the opportunity for first mover deployment of green hydrogen-based direct reduction and electric arc furnace (H2 DRI-EAF) capacity that can achieve the desired emission profile. Domestically, increasing adoption of Scope 3 targets among Japanese corporates — and the recent Scope 3 disclosure requirement by the Sustainability Standards Board of Japan (SSBJ) for publicly traded companies with a market capitalization over US$20 billion (with this requirement decreasing to US$6 billion starting in 2028) — signal that demand could be rising.5
The Japanese steel sector also faces several structural challenges, including competition from low-cost Chinese steel and declining profit margins stemming from global overcapacity. Leveraging product differentiation to capture green markets will be key to increasing competitiveness. While China is predicted to have a relative cost advantage,6 most of China’s hydrogen-based steelmaking is expected to serve local demand, leaving an opening for Japanese steel producers to capture this green segment in other markets.7 With 43 Mt of blast furnace capacity up for reinvestment in the next five years, Japanese steel producers can either reline and risk locking in coal-based production for decades, or transition to cleaner production pathways to capture growing green demand and stay competitive amid tightening carbon regulations.
In this analysis, we test the impact of Japan’s current and planned policy mix on the costs of various steel production routes from 2026 to 2050 to identify the most impactful instruments for deploying clean technologies in the steel sector.
Japan’s Green Steel Policy Mix Is Emerging in Response to Sector Transition Needs
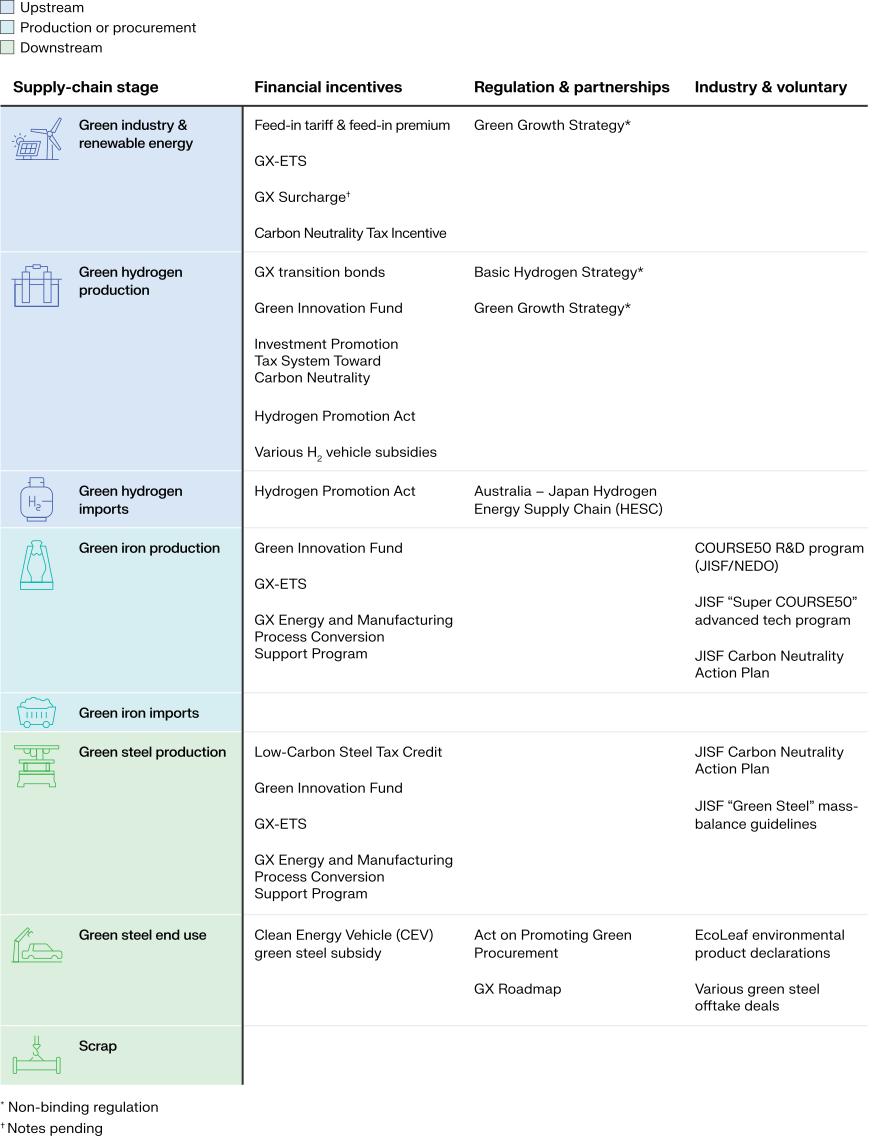
The Japanese government has established and planned policy interventions throughout the supply chain to address the green premiums and support a sector-wide transition (details in Exhibit A1 in the Appendix). These include tax credits, capital and research and development (R&D) subsidies, carbon pricing, and other mechanisms. Most major subsidies currently focus on transitioning existing BFs to EAFs: in 2025, major steelmakers JFE and Nippon Steel received US$2.2 billion in combined subsidies for EAF expansion.8
An overview of the key policies modeled in this brief is shown in Exhibit 1.9 Fossil fuel subsidy removals have not been passed or proposed but were modeled to explore the hypothetical impact of changing fuel costs.
Exhibit 1
Expected Policies Still Leave Near-Zero Steel at a 32%–62% Green Premium in 2035
With current and expected policies, our analysis shows that H2 DRI-EAF steel does not break even with BF-BOF production by 2050 (Exhibit 2). In 2035, when the EU CBAM is expected to operate at full force, domestic H2 DRI-EAF production still costs 62% more than the BF-BOF route. Domestic steel production using green iron sourced from Australia costs less but remains at a 32% cost premium. This analysis assumes an optimistic hybrid case with some grid connection for domestic green hydrogen projects in Japan; the premium for domestic H2 DRI-EAF production could increase even further, to 71%, if assuming a fully behind-the-meter green hydrogen case.
Domestic steel production with EAF using natural gas hot-briquetted iron (HBI) from the United States (NG DRI-EAF) is consistently at a lower cost than the hydrogen-based routes, but could be subject to price exposure. NG DRI-EAF steel only reduces emissions by 35% (or 23% if based on a 20-year global warming potential for upstream methane leakage), raising additional concerns around natural gas products’ ability to meet global emission standards with tightening carbon regulations in many markets.
On the other hand, scrap EAF production can undercut BF-BOF steel production costs with expected policies. However, scrap EAF cannot serve the volumes exposed to CBAM, including flat products such as hot-rolled and cold-rolled coils. Furthermore, certain steel products (e.g., most auto plates) still require input of ore-based metallics to meet specifications and safety regulations. The share of ore-based metallics in end-use steel products is over 50% for the construction sector, and over 80% for other sectors, resulting in an estimated 43 Mt of demand for ore-based metallics today (and about 56 Mt of projected demand in 2035).10
Additional policy support will be needed beyond what is currently in place to bring ore-based, low-emission steel premiums closer to buyers’ willingness to pay by 2035 and incentivize the deployment of more clean production capacity in coming years.
Exhibit 2
The impact of these individual policies on the green steel premium in 2035 is disaggregated in Exhibit 3 to show the effect of each policy.
Exhibit 3
Assuming that BF-BOF products (with incremental reduction measures like H2 injection) and NG DRI-EAF products are not eligible, the end-use clean energy vehicle (CEV) tax credit for green steel has the largest impact, significantly reducing or completely covering the green premium by 2035. However, the CEV credit applies only to battery-electric vehicles (BEVs), plug-in hybrids (PHEVs), and fuel cell vehicles, which currently only account for 2.4% of Japan’s domestic automobile sales (0.4 Mt of total steel use). Even assuming a high 15% annual growth rate in the sales of BEVs and PHEVs, the total amount of steel use would only amount to 1.6 Mt in 2035. The second-most impactful policy for ore-based routes is the low-carbon steel tax credit. However, this impact is also conditional on products made using the BF-BOF or NG DRI-EAF route not qualifying for the credit, which is not necessarily the case under the current GX Steel internal carbon banking methodology.11
Regarding capital subsidies, the Green Innovation Fund research and development (R&D) subsidy is markedly less impactful than production or end-use tax credits (resulting in a reduction of only 1% or less in the premium for ore-based routes). The Green Innovation Fund also has a separate ~US$150 million R&D fund for blast furnace hydrogen injection technology, which can only reduce emissions by 13%. The GX Promotion Act, which has issued US$1.76 billion and US$710 million to Nippon Steel and JFE for upcoming BF to EAF conversion projects, respectively, is much more impactful. As seen in Exhibit 3, the scrap-based route, with a smaller premium, benefits most from this subsidy. While support for deployment of EAFs will set up the steel industry well for transition, making targeted investments in ore-based routes is also necessary for market transformation.
Similarly, while lowering renewable electricity costs by 8% proves marginally more effective than removing existing domestic subsidies for coal and natural gas, upstream fuel subsidies (or removals of subsidies) have an overall minimal impact on reducing green premiums, as the cost of green hydrogen in H2 DRI-EAF remains proportionally high.12 The hydrogen contract-for-difference (H2 CfD) scheme (US$19 billion in total funding) has no impact, since it is likely that sectors with a lower cost gap between conventional fuels and green hydrogen (e.g., trucking, shipping, and fertilizer) will outbid steelmakers in the reverse auction system, thus leaving minimal funds available for the steel sector’s hydrogen demand.
Finally, in its current design, Japan’s GX-ETS is not expected to have a large impact on the green premiums for ore-based routes, with only a 2%–3% reduction in cost premiums over BF-BOF in 2035, because of low expected carbon prices and high product benchmarks. The GX-ETS price ceiling for the 2026–2029 period (US$29 per ton of carbon dioxide, or CO2) is roughly 68% lower than the 2025 average EU ETS price (US$83/tCO2).13 Product benchmarks are estimated to be around 1.8 tCO2/t HRC for the BF-BOF route during the first few years of implementation, meaning only ~0.1 tCO2/t HRC will be priced. Decreasing these benchmarks to gradually cover all product emissions (including Scope 2 and 3 emissions) will be critical to incentivize a faster deployment of clean technologies.
Stronger Policy Design Could Reduce Green Premiums to Below 20%
Assuming higher carbon prices, EU-aligned GX-ETS product benchmarks, earmarked H2 CfD funds for the steel sector, and a 10-year extension to the low-carbon steel tax credit, costs for H2 DRI-EAF using Australian green HBI are only at an 18% premium over BF-BOF in 2035, which may be within some buyers’ willingness to pay (see Exhibit 4).14 Assuming voluntary willingness-to-pay or other end-use incentives covering this remaining ~20% premium, H2 DRI-EAF with Australian green HBI could compete with BF-BOF. Domestic H2 DRI-EAF still maintains a high premium over BF-BOF, at 40% in 2035. Scrap EAF production is also 16% cheaper than BF-BOF production by 2035. However, when the tax credit and H2 CfD schemes conclude, a ~20% premium still remains for H2 DRI-EAF made with Australian green HBI from 2040 to 2050, illustrating the need for supplementary measures that can provide long-term support for cleaner production pathways.
Exhibit 4
Recommendations
With competitive pressure from global overcapacity, tightening carbon regimes, and low-cost Chinese steel on the one hand, and opportunities to capture growing green demand on the other, product differentiation may be key to enhancing competitiveness for Japanese steel producers. Transitioning the steel sector toward cleaner production also creates opportunities for value creation along the clean steel supply chain. Current and planned policies tested in this analysis (i.e., the low-carbon steel tax credit, Green Innovation Fund, and GX-ETS) show that these policies as currently designed still leave a significant cost gap between H2 DRI-EAF and BF-BOF production in 2050.
Although further analysis will be needed to carefully design a policy mix that is fiscally efficient and impactful, we propose several measures (Exhibit 5) that can support the deployment of some initial clean volumes to help Japan capture growing green demand and maintain access to markets with carbon regimes.
Exhibit 5
Preliminary recommendations for enabling policies
| Policy Mechanisms | Detail |
|---|---|
| End-use Incentives |
|
| Green Public Procurement |
|
| GX Steel & Internal Carbon Bank Emissions Accounting Methodology |
|
| Strategic Green Iron (H2 DRI) Sourcing |
|
Other considerations include incorporating decreasing product-level benchmarks and an emissions cap under GX-ETS and raising the GX-ETS price floors and ceilings. Developing a clear policy framework for embodied carbon regulations beyond the upcoming life-cycle assessment mandate for buildings can also enable the construction and real estate sectors to make informed investments in low-emission products, likely opening up a significant demand segment for clean steel.
Appendices
Appendix A. Policy Details
Exhibit A1
Extended list of policies along steel supply chain
Appendix B. Modeling Methodology and Assumptions
Exhibit B1
Exhibit B2
Note: The Hydrogen CfD Scheme fund includes ¥3 trillion (US$19 billion) allocated over 15 years (US$1.2 billion per year). For hydrogen products to qualify, they must have an emissions intensity of 3.4 kg-CO2e/kg-H2 or lower (well-to-gate, representing a 70% reduction from gray H2). To estimate the impact of the H2 CfD, the authors assumed that sectors with smaller cost gaps between conventional fuels and green hydrogen would be the first recipients of H2 CfD funding, covering the highest willingness-to-pay sector’s total demand before allocating to other sectors.17 Green demand estimates are based on sector-specific targets and/or nationally determined contribution targets. Hydrogen costs are expected to decrease as electrolyzer technology becomes deployed for various sectors, which will change the estimated cost gaps between conventional fuel costs and green hydrogen.
Endnotes
- World Steel in Figures 2025, World Steel, 2025, https://worldsteel.org/wp-content/uploads/World-Steel-in-Figures-2025.pdf. ↩︎
- Abhishek Shivakumar, Alastair Jackson, and Akira Kanno, Decarbonising the Steel Industry: Modelling Pathways in Japan, Transition Zero and Transition Asia, 2025, https://www.transitionzero.org/insights/decarbonising-the-steel-industry-modelling-pathways-in-japan; World Steel in Figures 2025, 2025. ↩︎
- Based on RMI analysis using current export volumes, announced EU CBAM benchmarks, and projected allowance prices. ↩︎
- “UN Comtrade Database,” United Nations, 2025, https://comtradeplus.un.org/. ↩︎
- “Japanese Regulator Finalises Law That Requires Sustainability Reporting Aligned with ISSB Standards,” Deloitte, 2026, https://www.iasplus.com/en/news/2026/02/japan-issb. ↩︎
- Ali Hasanbeigi et al., Green Steel Economics, Global Efficiency Intelligence, Transition Asia, and Solutions for Our Climate, 2024, https://www.globalefficiencyintel.com/green-steel-economics. ↩︎
- “Automakers Drive China Green Steel Development,” Lead the Charge and Transition Asia, 2025, https://leadthecharge.org/resources/greensteelchinacasestudy/. ↩︎
- Kenta Kubokawa and Sala Tsuzuki, “Japan Yearly Policy Review: Fiscal Year of 2025,” Transition Asia, 2026, https://transitionasia.org/japan-yearly-policy-review-fiscal-year-of-2025. ↩︎
- Importantly, Japan’s green steel definition, “GX Steel,” uses the internal carbon bank approach to report product-level emissions. This method allows for the pooling of emissions savings across sites, typically from incremental interventions (e.g., efficiency measures or partial fuel substitution at coal-based blast furnaces) at fossil-intensive facilities that cannot result in a near-zero emissions product intensity on their own. ↩︎
- “LCA Eco-Profiles — 2024 Release,” World Steel Association, 2024, https://worldsteel.org/wider-sustainability/life-cycle-thinking/lca-eco-profiles-2024-release/; World Steel in Figures 2025, 2025. ↩︎
- Yuko Nishida, “Remaining Challenges for Mass Balance Products,” Renewable Energy Institute, 2025, https://www.renewable-ei.org/en/activities/column/REupdate/20251023.php. ↩︎
- Subsidy values in dollars per gigajoule (US$/GJ) are calculated by dividing the total subsidy for a fuel (US$ millions) with national consumption of the fuel in 2025. OECD, “Fossil Fuel Support,” 2025, https://www.oecd.org/en/topics/sub-issues/fossil-fuel-support.html. ↩︎
- Aliana Zulaika Yeong, “Japan’s GX-ETS Mandatory Phase Begins; Demand Muted as Companies Await Allocation Clarity,” S&P Global, 2026, https://www.spglobal.com/energy/en/news-research/latest-news/energy-transition/040826-japans-gx-ets-mandatory-phase-begins-demand-muted-as-companies-await-allocation-clarity; “EU Emissions Trading System (EU ETS),” International Carbon Action Partnership, 2026, https://icapcarbonaction.com/en/ets/eu-emissions-trading-system-eu-ets. ↩︎
- Jake Stones, “Stegra Signs ‘Very Important’ Seven-Year Offtake Deal for Green Steel with Microsoft,” ICIS, 2025, https://www.icis.com/explore/resources/news/2025/09/26/11141130/stegra-signs-very-important-seven-year-offtake-deal-for-green-steel-with-microsoft/. ↩︎
- The Ministry of Land, Infrastructure, Transport and Tourism announced in July 2026 that it would procure 2,000 tons of GX steel for six civil construction projects starting in 2030, but as discussed above, to incentivize deployment of technologies that can meet global emission thresholds, public procurement programs should incentivize IEA near-zero aligned steel as possible. “Six Govt-Sponsored Civil Engineering Projects in Japan to Consume Around 2,000 t of Green Steel,” BigMint, 2026, https://www.bigmint.co/insights/detail/six-govt-sponsored-civil-engineering-projects-in-japan-to-consume-around-2-000-t-of-green-steel-775606. ↩︎
- “Corporate Net-Zero Standard V2.0,” Science Based Targets initiative, 2026, https://sciencebasedtargets.org/corporate-net-zero-standard-v2. ↩︎
- “Case Study — Japanese Government Subsidy Scheme / Government of Japan,” OECD, 2024, https://www.oecd.org/content/dam/oecd/en/about/programmes/cefim/green-hydrogen/2024-case-studies/Subsidy-scheme-Japan-case-study-2024.pdf; “Japan Awards US$6.8 Billion in First International Hydrogen CfD, Signaling Start of Major Procurement Cycle,” Wood Mackenzie, 2026, https://www.woodmac.com/press-releases/japan-hydrogen-cfd-2025/. ↩︎
日本のグリーンスチールのチャンスをサポートするより優れた政策
日本における低排出製鋼に対する政策のインパクトの分析
主な考察
よりクリーンな製鋼への移行は、回復力と競争力を構築する
日本は世界第3位の鉄鋼生産国であり、2024年には8400万トン(Mt)の粗鋼を生産している1。鉄鋼部門は現在、日本の総排出量の14%を占めており、石炭ベースの高炉-転炉法(BF-BOF)は生産量の74%を占めている2。欧州連合(EU)の炭素国境調整メカニズム(EU CBAM)などの政策により、2026年から2050年にかけて日本の経済価値はそのうち推定140億米ドルから280億米ドルがリスクにさらされるため、排出集約型の製鉄業はコストの上昇に直面するだろう3。
オーストラリア、カナダ、英国など、日本から鉄鋼を輸入する国は、CBAMを検討または積極的に実施している。これはさらに年間100万トン近くの輸出をリスクにさらす4。EUがCBAMの対象を一部の最終財に用いられた鋼材にも拡張することを検討しているため、このリスクは増加する可能性がある。日本で最近制定された排出量取引制度(GX-ETS)も、今後数年間に追加コストとなることが予想されている。
同時に、低排出鋼の需要は世界的に増加している。アジア太平洋(中国とインドを除く)、ヨーロッパ、北米が自発的にエネルギーや資源の消費(需要)をほぼゼロに抑えたとして、2030年には需要が約2000万トンになると推定される。この推定需要の約80%は鉄鉱石ベースの製品であることから、理想的な排出プロファイルを達成できる、グリーン水素ベースの直接還元および電気アーク炉(H2 DRI-EAF)能力を先行配備するチャンスが大きくなっている。国内では、日本企業のスコープ3ターゲットの採用が増加しており、時価総額が200億米ドルを超える上場企業に対しては日本のサステナビリティ基準委員会(SSBJ)の基準による最近のスコープ3開示要件(この要件は2028年から60億米ドルに引き下げ)があり、これが示すところでは、低排出鋼の需要が増加している可能性がある5。
日本の鉄鋼部門はまた、低コストの中国鋼材との競争や、世界的な過剰生産能力に起因する利益率の低下など、いくつかの構造的課題に直面している。グリーン市場を獲得するために製品の差別化を活用することが、競争力を高めるための鍵となる。中国は相対的なコスト優位性があると予測されているが6、中国による水素ベースの鉄鋼製造の大部分は現地需要に応えるために使われることが予想され、日本の鉄鋼生産者が他の市場でこのグリーンセグメントを獲得する機会はまだ残されている7。今後5年間、4300万トンのBF能力に再投資するか否かで、日本の鉄鋼生産者は、石炭ベースの生産を数十年にわたって支援し、それだけに固定されるリスクを負うか、よりクリーンな生産経路に移行して、成長するグリーン需要を捕捉し、炭素規制が厳格化する中でも競争力を維持するか選ぶことができる。
この分析では、2026年から2050年までのさまざまな鉄鋼生産ルートのコストについて、日本で現在すでに存在する、または今後計画されている政策の組み合わせによる影響をテストし、鉄鋼部門でクリーン技術を展開するために最も影響力のある手段を特定する。
日本のグリーンスチール政策の組み合わせは、セクターのトランジション・ニーズに対応して出現
日本政府は、グリーンプレミアムに対処し、セクター全体のトランジション、つまり移行を支援するために、サプライチェーン全体に政策介入することを計画している(詳細は別紙の付属A1)。これには、税額控除、設備投資および研究開発(R&D)補助金、カーボンプライシング、その他のメカニズムが含まれる。多くの主要な補助金は、現存するBFをEAFに移行することに焦点を当て、主要な製鉄会社であるJFEと日本製鉄は、EAF拡大のため、合計22億米ドルを受け取った8。
この文書で使用されている主要な政策の概要は、下に示す付属書類1に示されている9。化石燃料に対する補助金の廃止は承認あるいは提案されていないが、燃料にかかる費用が変化することによる、仮説的な影響が検証されている。
添付書類1
予想される政策を採用しても、2035年ニアゼロスチールのグリーンプレミアムは32%〜62%
現行および予想される政策を採用した場合、本分析を見ると、2050年までにBF-BOF生産を開始したとしてもH2 DRI-EAF鉄鋼と収益分岐点に達しない(添付書類2)。EU CBAMが全面導入されることが予想される2035年においても、国内のH2 DRI-EAF生産は依然としてBF-BOFルートよりも62%割高である。オーストラリア産のグリーン熱間成形還元鉄(HBI)を使った国内製造は、これより安価であるが、それでも32%割高である。この分析は、日本の国内グリーン水素プロジェクトの一部が既存電力網接続となる、という楽観的なハイブリッドケースを想定している。国内でH2 DRI-EAF生産を行うとして、完全にビハインドザメーターであるグリーン水素のケースを想定した場合、さらに71%まで増加する可能性がある。
アメリカからの天然ガスHBIを使った、EAFによる国内での鋼材製造(NG DRI-EAF)は、水素ベースの経路より一貫して低価格であるが、天然ガスの価格に左右される。NG DRI-EAF鋼は、排出量を35%削減するに止まり(あるいは、上流においてメタン漏れが生じる可能性を考慮しGWP20で計算するとする、23%)、多くの市場で炭素規制が厳しくなる中、天然ガス製品が世界の排出基準を満たす能力に対してさらなる懸念を引き起こす。
一方、スクラップEAFによる生産は、予想される政策が施行された場合、BF-BOF鋼の生産コストを下回る可能性がある。ただし、スクラップEAFは、熱間圧延および冷間圧延コイルといった薄板を含む、CBAMの対象となる供給量すべて製品を提供することはできない。さらに、特定の鉄鋼製品(多くのオートプレートなど)は、仕様と安全規制を満たすために鉄鉱石ベースの投入を依然として必要としている。鉄鉱石ベース半製品が最終用途の鉄鋼製品に占める割合は、建設部門で50%以上、その他の部門で80%以上であり、今日の鉄鉱石ベース製品の需要は推定4300万トン(2035年の予測需要は約5600万トン)に達している10。
鉄鉱石ベースの低排出鉄鋼にかかるプレミアムを2035年までに購入者の希望価格に近づけ、今後よりクリーンな生産能力の展開を促進するために、現在実施されているものを超えた、さらなる政策支援が必要になる。
添付書類2
2035年のグリーンスチールプレミアムに対するこうした個々の政策の影響は、各政策の効果を示すために添付書類3で分類した。
添付書類3
BF-BOF製品(H2吹き込みなどの段階的な削減措置を含む)およびNG DRI-EAF製品が対象外であると仮定すると、グリーンスチールの最終用途クリーンエネルギー自動車(CEV)税額控除が最大の影響を与え、2035年までにグリーンプレミアムを大幅に削減または完全に相殺するだろう。しかし、CEV税額控除はバッテリー電気自動車(BEV)、プラグインハイブリッド(PHEV)、燃料電池自動車にのみ適用され、現在、日本の国内自動車売上高(鉄鋼総使用量の40万トンに相当)に占める割合は2.4%に過ぎない。BEVやPHEVの売上高が年率15%という高成長率を遂げたとしても、2035年における鉄鋼総使用量は160万トンに過ぎない。鉄鉱石を主原料として利用する方法の中で、2番目に影響力のある政策は、低炭素鉄鋼税額控除である。ただし、この影響は、BF-BOFまたはNG DRI-EAFを利用して作られた製品が税控除の対象にならないことも条件となる。これは、現行のGXスチールのインターナルカーボンバンキング手法では必ずしも当てはまらない11。
設備投資補助金に関しては、グリーンイノベーション基金の研究開発(R&D)補助金は、生産税額控除または最終用途税額控除よりも著しく影響が小さい(結果として、鉄鉱石を主原料として利用する方法の中では、プレミアムの1%以下しか削減できない)。グリーンイノベーション基金は、BFへの水素吹き込み技術のために最大約1億5000万米ドルの研究開発基金も別枠で設けてあるが、排出量は13%低減するに過ぎない。GX推進法は、今後BFからEAFに転換するためのプロジェクトに対して、それぞれ17億6,000万米ドルと7億1,000万米ドルを日本製鉄とJFEに与えたが、これはかなり影響力がある。添付書類3に見られるように、プレミアムがより小さい、スクラップを利用した方法は、この補助金から最も利益を得る。EAFの展開を支援することで、鉄鋼業界は移行準備ができるが、市場変革のためには、鉄鉱石を主原料として利用する方法に対して投資を行うことも必要である。
同様に、再生可能エネルギー由来電力にかかる経費を8%削減できれば、石炭と天然ガスに対する既存の国内補助金を撤廃するよりも効果的であることが証明されている。ただし上流の燃料補助金(または補助金の撤廃)は、H2 DRI-EAFにおけるグリーン水素のコストが比例して高いところで維持されるため、グリーンプレミアムの削減全体に及ぼす影響は最小限である12。水素差額契約(H2 CfD)計画(総資金調達額は190億米ドル)は、従来の燃料とグリーン水素との価格差が少ないセクター(トラック輸送、海運、肥料など)がリバースオークションシステムで鉄鋼メーカーを競り落とすことができるため、鉄鋼セクターの水素需要に利用できる資金が最小限にとどまる可能性が高く、影響がない。
最後に、現行のデザインにおける日本のGX-ETSは、鉄鋼を主原料として利用する方法の中で、グリーンプレミアムに大きい影響力があるとは予想されていない。2035年にはBF-BOFに比べたプレミアムの削減は2%〜3%に過ぎない。これは予想される炭素価格が低く、製品のベンチマークが高いためである。2026〜2029年におけるGX-ETS価格の上限(二酸化炭素[CO2]1トンに対して29米ドル)は、EU ETS価格(83米ドル/tCO2)よりおよそ68%低い13。製品のベンチマークは実装から最初の数年間のBF-BOF経路では、およそ1.8 tCO2/t HRCと予想され、~0.1 tCO2/t HRCのみが価格付けされることを意味する。これらのベンチマークを低減し、徐々に全ての製品から生じる排出をカバーすること(スコープ2およびスコープ3排出を含む)が、クリーン技術をより迅速に展開するためのきっかけを作るために必要不可欠である。
より強い政策デザインは、グリーンプレミアムを20%未満にする可能性がある
炭素価格の引き上げ、EUに準拠したGX-ETS製品のベンチマーク、鉄鋼部門向けのH2 CfD資金の指定、および低炭素鋼材にかかる税額控除の10年間延長を仮定として置くと、オーストラリアのグリーンHBIを使用したH2 DRI-EAFのコストプレミアムは、2035年のBF-BOFに対して18%に過ぎない。これは一部のバイヤーが購入する範囲に十分入る可能性がある(添付書類4参照)14。残りの~20%のプレミアムを自発的に支払う意欲がある企業、または支払いを促すその他の最終用途インセンティブを想定した場合、H2 DRI-EAFをオーストラリア産グリーンHBIに組み合わせると、BF-BOFと競争力を有する可能性がありえる。国内のH2 DRI-EAFは依然としてBF-BOFよりも高いプレミアムを維持することになり、2035年には40%とされる。また、スクラップEAFによる生産は、2035年までにはBF-BOF鋼の生産コストを16%下回る。しかし、税額控除とH2 CfD計画が終了すると、2040年から2050年にかけて、オーストラリアのグリーンHBIで作られたH2 DRI-EAFには、~20%のプレミアムが残り、よりクリーンな生産経路を長期的にサポートできる補完措置の必要性が示されている。
添付書類4
推奨事項
一方では、世界的な過剰生産能力、CO2管理体制の引き締め、そして中国の低価格鉄鋼に由来する競争上の圧力、そして他方では、成長するグリーン需要を捉える機会がある中、日本の鉄鋼生産者の競争力を高めるためには、製品差別化が鍵となりえる。鉄鋼部門をよりクリーンな生産に移行させることは、クリーンスチールサプライチェーンとともに価値創造の機会を生み出す。本分析でテストされた現行の、また計画されている政策(すなわち、低炭素鉄鋼税額控除、グリーンイノベーション基金、およびGX-ETS)は、いまその政策が行われた場合、2050年においても、H2 DRI-EAFおよびBF-BOF生産の間に残る大きなコストギャップを埋めるに不十分であることを示している。
財政的に効率的でインパクトのある組み合わせの政策を慎重に設計するためにはさらなる分析が必要である。ここで、伸びつつある、グリーン需要を捉え、CO2管理体制を持つ市場へのアクセスを維持するために役立つ、日本が実行可能な、初期におけるクリーンスチール生産量の展開の一部をサポートするいくつかの措置(添付書類5)を提案する。
添付書類5
政策を実施するための暫定的推奨事項
| 政策の構造 | 詳細 |
|---|---|
| 最終用途に対するインセンティブ |
|
| グリーンな公共調達 |
|
| GXスチール&インターナルカーボンバンク排出量会計方法論 |
|
| 戦略的グリーンアイアン(H2 DRI)調達 |
|
その他の考慮事項としては、製品レベルのベンチマーク低減を取り込むこと、およびGX-ETSに排出量上限を設ける、そしてGX-ETSの下限と上限価格を引き上げることである。さらに、今後の建築物ライフサイクル評価義務を超えて、エンボディドカーボン規制のために明確な政策の枠組みを作り、それによって建設セクターと不動産セクターが低排出製品に対して、情報に基づいた投資を行うことも可能になり、クリーンスチールに非常に強い需要をもたらす可能性がある。
別紙
別紙A 政策の詳細
添付書類A1
鉄鋼サプライチェーンに沿った政策の拡張リスト

別紙B モデリング手法論と仮説
添付書類B1
添付書類B2
注:水素CfD計画では、15年にわたり、3兆円(190億米ドル)が拠出される(1年で12億米ドル)。水素製品が適格となるには、排出強度が3.4 kg-CO2e/kg-H2以下でなければならない(ウェルトゥーゲート、グレーH2から70%の削減に相当)。H2 CfDの影響を推定するために、著者は、従来の燃料とグリーン水素との間のコストギャップが小さいセクターがH2 CfD資金の最初の受領者となり、他のセクターに割り当てる前に、最も高い支払い意欲を持つセクターの総需要をカバーすると仮定した17。グリーン需要の推定は、セクター固有の目標または国が決定した貢献(NDC)目標に基づいている。水素コストは、様々なセクターに対して電解槽技術が展開されるにつれて低減すると予想され、これにより従来の燃料コストとグリーン水素の推定コストギャップが変化する。
文末脚注
- World Steel in Figures 2025, World Steel, 2025, https://worldsteel.org/wp-content/uploads/World-Steel-in-Figures-2025.pdf. ↩︎
- Abhishek Shivakumar, Alastair Jackson, and Akira Kanno, Decarbonising the Steel Industry: Modelling Pathways in Japan, Transition Zero and Transition Asia, 2025, https://www.transitionzero.org/insights/decarbonising-the-steel-industry-modelling-pathways-in-japan; World Steel in Figures 2025, 2025. ↩︎
- 現在の輸出量を使用したRMI analysis、発表されたEU CBAMベンチマーク、および予測される排出枠の価格に基づく。 ↩︎
- “UN Comtrade Database,” United Nations, 2025, https://comtradeplus.un.org/. ↩︎
- “Japanese Regulator Finalises Law That Requires Sustainability Reporting Aligned with ISSB Standards,” Deloitte, 2026, https://www.iasplus.com/en/news/2026/02/japan-issb. ↩︎
- Ali Hasanbeigi et al., Green Steel Economics, Global Efficiency Intelligence, Transition Asia, and Solutions for Our Climate, 2024, https://www.globalefficiencyintel.com/green-steel-economics. ↩︎
- “Automakers Drive China Green Steel Development,” Lead the Charge and Transition Asia, 2025, https://leadthecharge.org/resources/greensteelchinacasestudy/. ↩︎
- Kenta Kubokawa and Sala Tsuzuki, “Japan Yearly Policy Review: Fiscal Year of 2025,” Transition Asia, 2026, https://transitionasia.org/japan-yearly-policy-review-fiscal-year-of-2025. ↩︎
- 重要な点として、日本のグリーンスチールの定義である「GXスチール」は、インターナルカーボンバンクアプローチを使用して製品レベルの排出量を報告している。この方法は、典型的には独立状態ではニアゼロ排出量の製品強度をもたらすことができない、化石集約型施設での斬進的な介入(例えば、石炭ベースの高炉での効率化措置または部分的な燃料代替など)による、サイト全体の排出削減の蓄積を可能にする。 ↩︎
- “LCA Eco-Profiles — 2024 Release,” World Steel Association, 2024, https://worldsteel.org/wider-sustainability/life-cycle-thinking/lca-eco-profiles-2024-release/; World Steel in Figures 2025, 2025. ↩︎
- Yuko Nishida, “Remaining Challenges for Mass Balance Products,” Renewable Energy Institute, 2025, https://www.renewable-ei.org/en/activities/column/REupdate/20251023.php. ↩︎
- ギガジュール当たりの補助金額(USD/GJ)は、1つの燃料に対する補助金総額(USD百万)を2025年の国内燃料消費量で割って計算される。OECD, “Fossil Fuel Support,” 2025, https://www.oecd.org/en/topics/sub-issues/fossil-fuel-support.html. ↩︎
- Aliana Zulaika Yeong, “Japan’s GX-ETS Mandatory Phase Begins; Demand Muted as Companies Await Allocation Clarity,” S&P Global, 2026, https://www.spglobal.com/energy/en/news-research/latest-news/energy-transition/040826-japans-gx-ets-mandatory-phase-begins-demand-muted-as-companies-await-allocation-clarity; “EU Emissions Trading System (EU ETS),” International Carbon Action Partnership, 2026, https://icapcarbonaction.com/en/ets/eu-emissions-trading-system-eu-ets. ↩︎
- Jake Stones, “Stegra Signs ‘Very Important’ Seven-Year Offtake Deal for Green Steel with Microsoft,” ICIS, 2025, https://www.icis.com/explore/resources/news/2025/09/26/11141130/stegra-signs-very-important-seven-year-offtake-deal-for-green-steel-with-microsoft/. ↩︎
- 国土交通省は2026年7月に、2030年に始まる6つの土木建設プロジェクトで2,000トンのGXスチールを調達すると発表したが、上記で説明したように、世界的な排出基準を満たすことができる技術の展開を促進するために、公共調達プログラムはIEAのニアゼロスチールを可能な限り促進する必要がある。“Six Govt-Sponsored Civil Engineering Projects in Japan to Consume Around 2,000 t of Green Steel,” BigMint, 2026, https://www.bigmint.co/insights/detail/six-govt-sponsored-civil-engineering-projects-in-japan-to-consume-around-2-000-t-of-green-steel-775606. ↩︎
- “Corporate Net-Zero Standard V2.0,” Science Based Targets initiative, 2026, https://sciencebasedtargets.org/corporate-net-zero-standard-v2. ↩︎
- “Case Study — Japanese Government Subsidy Scheme / Government of Japan,” OECD, 2024, https://www.oecd.org/content/dam/oecd/en/about/programmes/cefim/green-hydrogen/2024-case-studies/Subsidy-scheme-Japan-case-study-2024.pdf; “Japan Awards US$6.8 Billion in First International Hydrogen CfD, Signaling Start of Major Procurement Cycle,” Wood Mackenzie, 2026, https://www.woodmac.com/press-releases/japan-hydrogen-cfd-2025/. ↩︎
Related Insights
How Better Policy Can Support South Korea’s Green Steel Opportunity
Help build the clean energy future. Donate today.
Independent research. Real-world solutions. Supported by donors.
RMI can pursue the highest-impact climate and energy solutions because we’re supported by people who believe change is possible. Every gift helps advance the work needed to make clean energy the default choice worldwide.
For other ways to give to RMI, including checks or gifts of stock, please visit Other Ways to Give.